

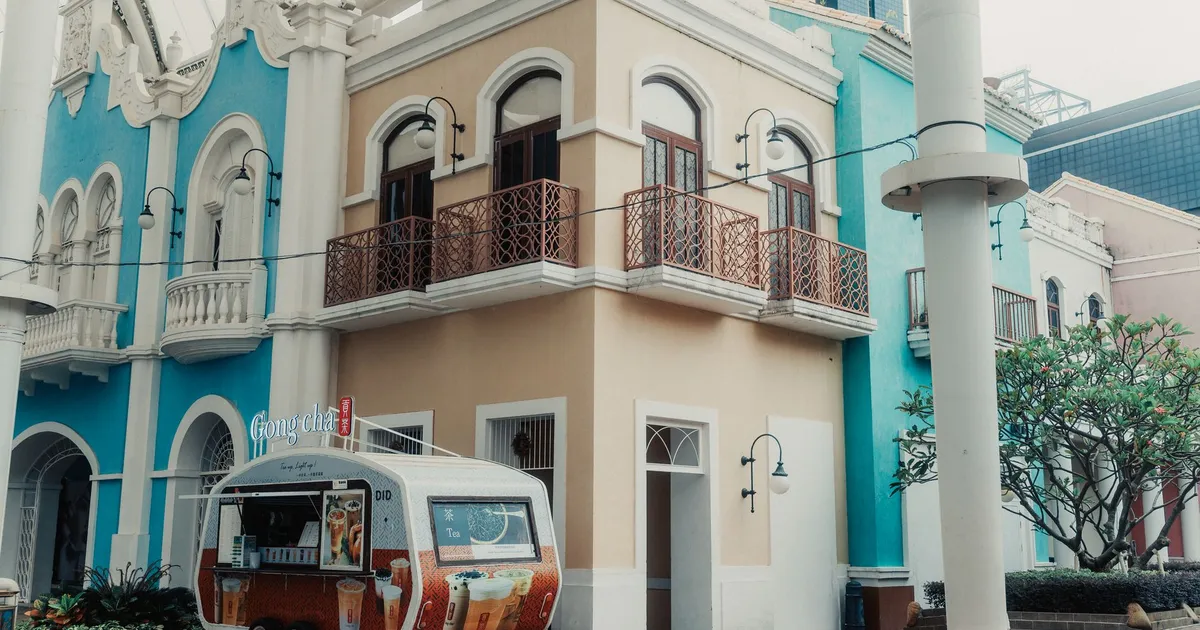
Gong Cha New Zealand has quietly shelved the growth story. The Taiwanese bubble tea chain now runs 30 stores, 18 in Auckland and 12 elsewhere, and management is now talking about “sustainable growth” instead of new openings. That phrase usually means one thing in franchising. The unit economics no longer justify the next lease.
The tell is the store count. Back in December 2024, The Spinoff put Gong Cha at 30 stores nationwide, nine years after it arrived here in 2015. Two years on, the number hasn’t moved. For a brand that sells itself on momentum, a plateau that long is a decision, not an accident.
The costs arrived before the customers did
GM Marcus Teh is candid about why. He told the Herald the business has faced “a challenging operating environment over the past few years”, pointing to cost-of-living pressure, higher interest rates and uncertainty squeezing discretionary spending, alongside rising wages, rent, insurance, utilities, ingredients, freight and logistics.
That list reads like the cost base of every hospitality operator in the country. What makes bubble tea especially exposed is the price ceiling. In 2025, a regular cost $7.50 and a large $8.50. Push much past that and the drink stops being an impulse treat and becomes a considered purchase, which is exactly what a cautious consumer cuts first.
The pain showed up at franchisee level well before the head office pivot. In 2025, Peter Zhao, who then ran three stores across Hamilton and Napier, said the business had weathered a slowdown since 2023 and summed it up bluntly: “It’s a bit low, but we can survive.” Survival is not a pitch that sells new franchises.
A crowded cup
Competition compounds the squeeze. Even in 2024 the local field included HuluCat, Yi Fang, Tea Talk, Wucha Lounge, Cha Time and TwenTea, a genuinely crowded category. The Herald now names CoCo and Teaser as direct rivals, and McDonald’s has rolled out an expanded “refreshers” range aimed at the same thirsty, mainstream customer. When the world’s biggest fast-food chain decides your category is worth a menu slot, your pricing power shrinks.
The model itself is under pressure
This is not just a Kiwi stumble. Globally, Gong Cha has been through four owners in roughly two decades, with Bain Capital agreeing this August to buy it from TA Associates. The business has recovered, posting FY2025 revenue of about US$217 million, up 14%, but that followed a rough 2023 in which it recorded a pre-tax loss of US$12.4 million.
The deeper threat is structural. Chinese chains such as Mixue, Guming and Chagee make their money supplying franchisees with tea, syrups, packaging and equipment, turning every store into a recurring product order. That vertical integration funds price competition a royalty-based licensor struggles to match. Inside Retail also reported Gong Cha’s entire Singapore network shut in October 2025 when its master franchise agreement lapsed, a reminder of how thin the licensing layer can be.
“A store a day” met reality
The ambition used to be very different. In 2023, then-global CEO Paul Reynish said great brands overcome inflation with scale, “which is why we’re building a store a day in 2023.” That year Gong Cha did open 159 net new stores, and lost money doing it.
Reynish also offered the better rule. Franchise growth, he said, is simple: “if you make money, you grow, and if you don’t, you won’t.” New Zealand’s stall is that principle working as intended. Franchisees and capital won’t fund the 31st store if the first 30 are grinding.
What business owners should take from it
Credit where it’s due. Pausing expansion rather than chasing a headline target is the disciplined call, and it protects existing franchisees from cannibalisation. The category isn’t dying either. Customers have broadened well beyond teenagers.
But the lesson for anyone running or buying into a discretionary concept is sharp. Trend appeal gets you to scale. It does not pay a Ponsonby lease, a Living Wage rise and a doubled insurance premium. Those costs are set by the economy, not the brand, and they are why even a 2,100-store global name has found its New Zealand ceiling.
What happens next depends on two things outside Gong Cha’s control: whether households regain spending confidence through 2027, and whether vertically integrated Chinese rivals make a serious push into New Zealand. If the second arrives before the first, 30 stores may turn out to be the high-water mark rather than the base camp.
Sources
- NZ Herald: Gong Cha shifts focus to sustainable growth after expansion plans stall (2026-11-14)
- The Spinoff: ‘Just like the pie’: Bubble tea is here to stay (2024-12-20)
- Waikato Times: Bestsellers: Bubble tea goes from curiosity to craving at Gong cha (2025-05-08)
- Inside Retail: Two decades, four owners: Gong Cha and the limits of the licensing model (2026-08-12)
- World Coffee Portal: Gong cha slips into the red amid falling sales in key South Korean market (2024-10-01)
Join the discussion
Add useful context, ask a good question, or challenge an idea — keep it specific and respectful.