

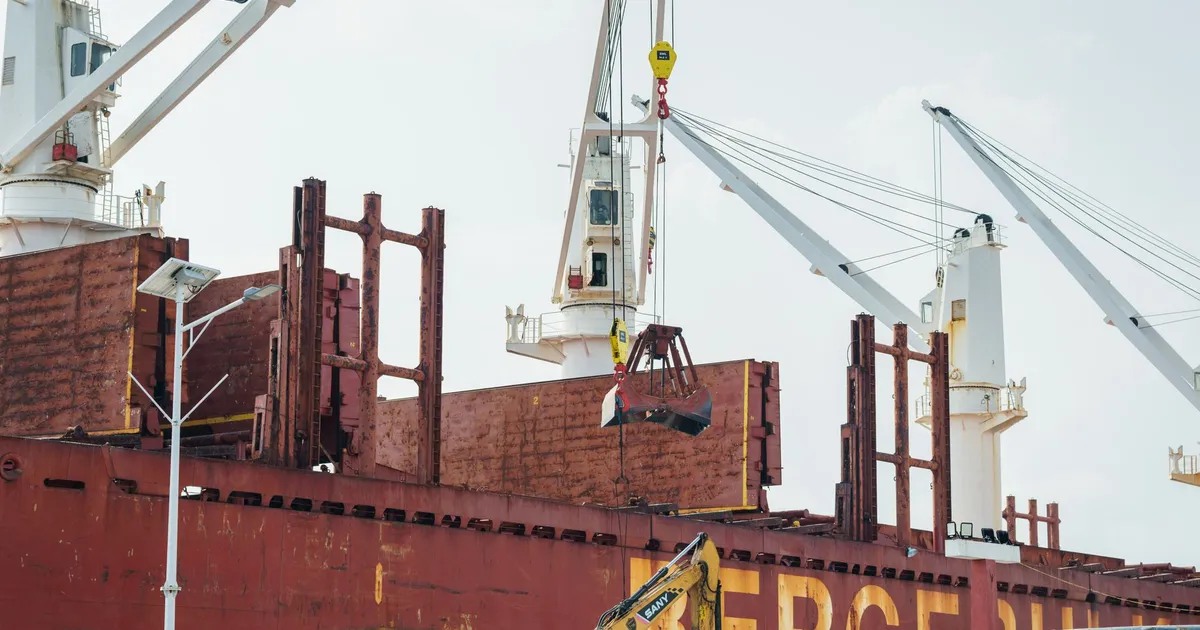
Environment Southland has done something most New Zealand councils only mention in long-term plan documents. It sold part of a strategic asset, at a good price, through a proper market process, and kept control.
The regional council told the NZX it has sold about 14.3% of its South Port shareholding at $8.00 a share, raising more than $30 million. Its stake in the company running Bluff’s deep-water port falls from 66% to about 52.2%, still a clear majority. BusinessDesk put the figure at $32 million, with Jarden as bookbuilder and underwriter and settlement due on 5 October. The 3.75 million shares sold at $8.00 come to roughly $30 million, which is the number that matches the primary disclosure.
This is asset recycling. It is not privatisation, and it is not a fire sale. Ratepayers should want more of it.
A mandate with conditions attached
This was not a panic move to plug a hole. During its 2024-34 long-term plan, the council consulted on cutting its stake from 66% to as low as 51%. The aim was to diversify income and reduce concentration risk, not to fund a pet project. When the council appointed a financial adviser in 2025, then-chief executive Stephen Hall said any decision would be “guided by prevailing market conditions, professional advisors, and ultimately the ability to achieve an appropriate financial outcome on behalf of ratepayers”. If the value was not there, the council would keep its shares.
That is the right way to give a council permission to sell. Set a floor, attach conditions, and walk away if the market does not pay.
Selling into strength
The market paid because South Port has never looked better. The company posted a record $16.1 million after-tax profit for FY2026, with cargo volumes nearing 4 million tonnes on the back of agricultural exports, Tiwai Point aluminium throughput and wind farm project cargo.
Critics will ask why you would sell a slice of a business at its peak. That is exactly when you sell. Council chair Jeremy McPhail said in September that any decision would depend on “whether a proposal could deliver an appropriate financial outcome for ratepayers”. After the deal, he was blunter. “Essentially, reducing our shareholding is about reducing risk by not having too many eggs in one basket,” he said, adding that the council’s analysis showed better returns from diversifying “especially at this time when South Port is doing well”.
A regional council with two-thirds of its investment exposure tied to one port, which depends heavily on one smelter, carries real concentration risk. Cutting that risk while the asset is priced at its best is basic portfolio management. Plenty of private investors would have done the same.
Where the money actually lands
This is where ratepayers get a direct return. Income from the council’s wider investment portfolio, which the proceeds now join, goes first to key reserves including a disaster recovery fund, and then to reducing general rates.
That link between an asset decision and the rates bill is what most councils fail to make. They treat their balance sheets and their rates increases as separate conversations. Southland’s farmers, contractors and port users can now trace a line from a share sale to their own rates.
The closed-door caveat
There is one fair criticism. Ahead of the announcement, the council held extraordinary investment committee and full council meetings on “South Port matters” with the public excluded. Transparency matters in local government. But this was a live, price-sensitive transaction in a listed company, and the principle of a sell-down had already been consulted on publicly. Running the pricing details through open meetings would have cost ratepayers money. On balance, the council got it right.
A template for the rest of the country
The wider fiscal picture makes this more than a Southland story. In 2025 Treasury reported a $4.4 billion operating deficit for 2024/25, with net core Crown debt at $182.2 billion, or 41.8% of GDP. Its 2025 investment statement noted that Crown physical assets grew 30% since 2021, with more than half of that from inflationary revaluation rather than new investment. Public balance sheets look larger on paper while the cash keeps getting tighter.
Councils face the same squeeze on a smaller scale, and most respond by raising rates and borrowing more. Many hold port, airport, forestry and property stakes that sit untouched because selling any part of them feels politically dangerous. Southland has shown a middle path. It kept control, brought in private capital and market discipline, and sold only on terms set in advance.
South Port now has a broader shareholder base and a council that still controls it. The next test is whether other councils with concentrated holdings and angry ratepayers copy this approach or keep claiming their only lever is the rates bill. Southland has shown the alternative works.
Sources
- NZX: South Port – Environment Southland Share Sale (2026-10-01)
- ODT: Partial sell-down of $30m in Bluff port shares still gives Environment Southland controlling interest (2026-10-01)
- BusinessDesk: Southland council sells $32m South Port stake amid record growth (2026-10-02)
- What’s On In Invers: Environment Southland Cuts South Port Stake For $30m (2026-10-01)
- Environment Southland: Financial advisor appointed (2025-07-29)
- Scoop: Regional Council Discusses Reducing Stake In Bluff Port Despite Record Profit (2026-09-08)
- ODT: Public shut out of port discussions at Southland council (2026-09-24)
Join the discussion
Add useful context, ask a good question, or challenge an idea — keep it specific and respectful.