
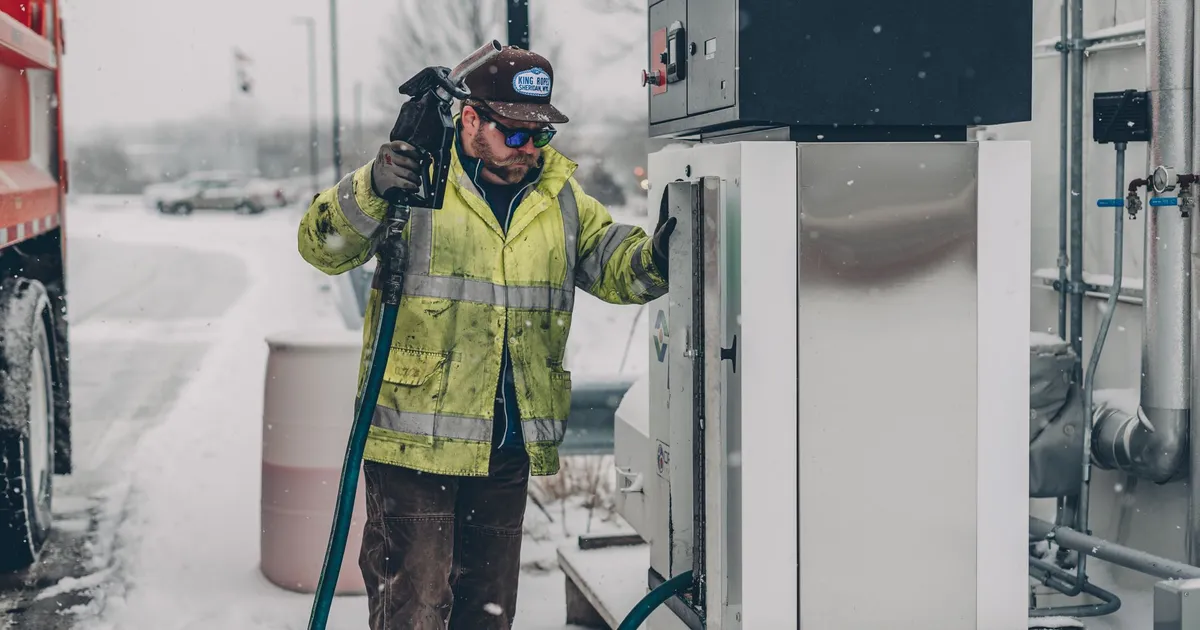
Regular 91 is now averaging $3.52 a litre nationwide, up 15.9% in 28 days, with diesel at $3.23 after an 18.25% jump. That is an outright all-time record for 91, clearing the previous high set in April after the US and Israeli strikes on Iran.
Most coverage frames this as a pain-at-the-pump story about commuters. For business owners, that is the least important part. The real damage runs through freight, trades, contractors and fleets, and the official data says most of it has not yet landed.
Diesel is where the economy actually feels it
“Diesel is the fuel of the economy, with approximately 93% of annual freight tonnage being moved by road,” says Transporting NZ’s Mark Stockdale, noting diesel rose more than 50 cents a litre in a single month.
Stats NZ’s producer price data shows what that does to cost bases. In the June quarter, diesel input costs rose 52.6% and road transport input costs 12.2%. Overall producer input prices rose 2.9%, but output prices only 1.6%. That gap is margin being eaten, quarter after quarter, by firms reluctant to pass costs on into soft demand.
Nobody at the forecourt is getting rich
Expect the election-season reflex to blame retailers. The Commerce Commission’s own numbers kill that argument. Between late February and 29 September, the average price-cost spread on 91 was 44 cents a litre, down from 51 cents in 2025. Diesel spreads fell to 47 cents from 55 cents. Margins have compressed while pump prices hit records.
The drivers are offshore. Brent crude sits at US$101.5 a barrel, while the kiwi has dropped about 7% since August to around 55.8 US cents. ASB acting chief economist Kim Mundy calls it a double hit, with “global oil prices high, and New Zealand dollar quite low, costing more from exchange rate perspective to import fuel.” Attacks on Russian refineries have also choked diesel exports from the world’s second-biggest producer, layering a second supply shock on the Middle East one.
Surcharges are the early warning
The clearest signal that costs are moving down the supply chain is on invoices. Rural Contractors New Zealand chief executive Andrew Olsen is urging members to use Fuel Adjustment Factor pricing, a line-item surcharge that tracks fuel rather than forcing constant requotes. Diesel is “a huge component of contracting business and rapid increases erode already competitive margins,” he says.
Strong dairy, meat and wool prices mean farmers are swallowing the surcharges for now. Couriers, hauliers, tradies and tourism operators selling into weaker markets will not find customers so accommodating.
The second round is still coming
Treasury is blunt. The fuel shock is expected to transmit more broadly as higher transport costs raise business input costs that are “passed through to the price of other goods and services over time.” Infometrics noted in August that fuel was still 45% above end-of-February levels and warned further rises could not be discounted. That warning has now come true.
The Reserve Bank has already acted. Annual inflation hit 4.1% in the June quarter, largely on fuel, and the OCR went up 25 basis points to 2.75%. So the oil shock now reaches businesses twice, through the fleet bill and the overdraft.
Not everyone thinks that is the right call. Simplicity chief economist Shamubeel Eaqub argues fuel inflation crowds out other spending rather than feeding a price spiral. “It just makes people poorer and they don’t have money to spend,” he says. If he is right, businesses face rising costs, tighter credit and weaker customers simultaneously.
A new levy is the wrong reflex
Transporting NZ wants diesel reserves doubled to 60 days and a Fuel Resilience Fund paid for by a new 1 cent per litre levy. Supply resilience is a fair concern after two shocks in one year. But a fresh per-litre tax at record prices, funding a government-run pot, is the kind of fix that outlives its purpose. Stockholding obligations on importers, diversified supply contracts and letting price signals work would buy security without another permanent charge at the pump.
What to do now
Treat this as a cost reset, not a spike. Check whether supplier contracts carry fuel clauses, build your own into quotes, and price on the assumption that freight costs keep rising into summer. The pump price is the headline. The invoice is the story, and it has barely started.
Sources
- RNZ: Fuel price hits tipping point (2026-10-07)
- RNZ: Petrol price hits highest level since start of Iran war (2026-10-05)
- 1News: Petrol price hits all-time-high as average litre of 91 tops $3.50 (2026-10-06)
- Farmers Weekly: Contractors urged to account for diesel spike (2026-10-05)
- Commerce Commission: Fuel Price Monitoring to 29 September 2026 (2026-10-01)
- Stats NZ: Input prices paid by producers increase 2.9 percent in the June 2026 quarter (2026-08-19)
- Transporting NZ: Fuel volatility reinforces need for fuel security (2026-09-29)
- Infometrics: Higher diesel prices dominate transport costs (2026-08-21)
Join the discussion
Add useful context, ask a good question, or challenge an idea — keep it specific and respectful.