
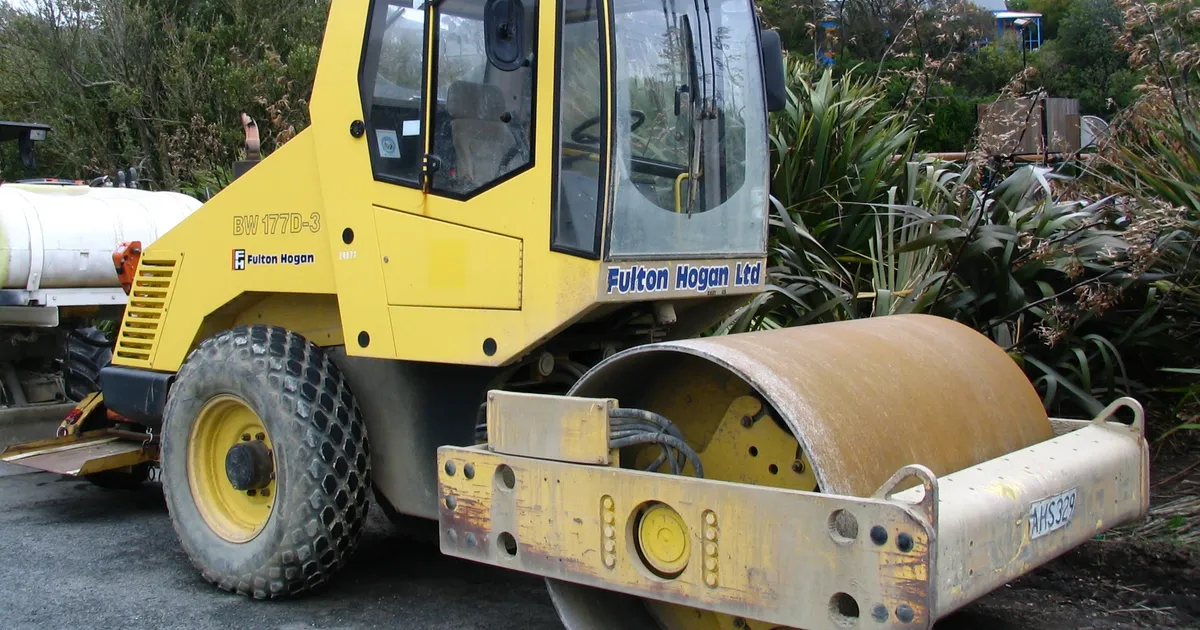
Fulton Hogan has just given the clearest evidence yet that New Zealand’s infrastructure pipeline is more than a slide deck. The contractor lifted after-tax profit from $365 million to $430 million in FY26, on revenue up from $6.9 billion to $7.3 billion, after a weak 2025.
That is a genuine win, and it should be read as one. But it is a win for civil contractors. Anyone reading it as proof that construction is back is reading the wrong result.
The money is flowing to roads, water and runways
Fulton Hogan’s New Zealand highlights are a list of public infrastructure work: SH1 Papakura to Drury, runway resurfacing at Dunedin and Invercargill airports, and growing water programmes from Auckland to Dunedin. This is the pipeline converting into invoices.
The wider data backs that up. Te Waihanga’s pipeline rose $15.6 billion between March and June to around $290 billion, with $71.2 billion of projects already under construction and 519 initiatives worth $12.7 billion in procurement. Transport alone is expected to account for $9.6 billion, or 46%, of infrastructure spending over the next year.
Pricing tells the same story. Civil construction costs rose 5.2% in the year to June, against 2.8% for residential and 2.2% for non-residential, according to RLB’s Q3 infrastructure forecast, which expects civil inflation to reach 6% by December. Cost inflation nearly double the rest of the sector means one thing: that is where the demand is.
Everyone else is still doing it hard
Infrastructure New Zealand chief executive Nick Leggett was quick to puncture any sector-wide celebration. He told Mike Hosking that Fulton Hogan does not represent the whole industry, which remains “a mixed bag”, with design and engineering firms still laying people off.
The numbers are grim further down the chain. RLB and NZIER’s latest forecast found a net 55% of building firms reported weaker profitability in the June quarter, a net 85% faced higher costs despite weak demand, and the report put it bluntly: the infrastructure pipeline “does not necessarily translate into stronger demand for vertical build contractors and subcontractors.”
Fletcher Building proves the point from the other direction. Its recovery to $414 million of EBIT and $228 million of net earnings came after it walked away from its loss-making Construction division altogether. One company got healthier by leaning into civil work. The other got healthier by getting out of building. Same split, opposite ends.
For subcontractors, architects and vertical builders, the lesson is uncomfortable. Government capital is real, but it is pouring into horizontal assets. If your order book depends on offices, apartments or commercial fit-outs, Fulton Hogan’s result is not your result.
Australia is pulling level
The sharper detail is where the profit came from. Fulton Hogan’s earnings are now evenly balanced between Australia and New Zealand, and chairman Dean Hamilton singled out the Tasman business as the highlight, saying Australia had reached “a new level of performance.”
That should focus minds in Wellington. Contractors allocate capital, plant and people to wherever pipelines are deepest and most certain. Of New Zealand’s $290 billion pipeline, only $95.8 billion is fully funded. The rest is committed or confirmed, which is not the same thing as cash in a contract.
To be fair, Fulton Hogan is still betting on New Zealand. It has just opened a $100m-plus asphalt plant at Horokiwi Quarry near Wellington, capable of 200 tonnes an hour, more than doubling regional output. The company said the plant would help it “meet future demand with confidence.” Long-life plant like that is a vote of confidence in a multi-year programme, not a single budget.
The risk is that confidence becomes conditional. Stop-start funding, slow procurement and projects that sit in “committed” for years are exactly what pushes a trans-Tasman contractor to tilt its next round of investment toward Sydney and Brisbane.
What to watch next
Fulton Hogan is privately held, with 3,867 shareholders, 2,705 of them employees, so detail arrives slowly. The full annual report, including the FY26 dividend, is expected after the AGM on 29 October.
That breakdown will show how much of the rebound is genuinely New Zealand-driven. For now the message is clear enough. The infrastructure pipeline is real and the biggest civil players are banking it. The government’s job is to turn more of that $290 billion from promise into funded contracts, fast enough that the next asphalt plant gets built here rather than across the ditch, and broad enough that the wider construction sector eventually feels it too.
Sources
- NZ Herald: Fulton Hogan revenues and profits rebound after 2025 downturn (2026-10-05)
- Newstalk ZB: A mixed bag in the construction sector as Fulton Hogan bounces back (2026-10-06)
- RLB: Infrastructure Forecast Report Q3 2026 (2026-08)
- RLB: Forecast Report 117 (2026-10)
- Fletcher Building: FY26 results stock exchange announcement (2026-08-19)
- Infrastructure News: Fulton Hogan opens new asphalt plant in Wellington (2026-09-14)
Join the discussion
Add useful context, ask a good question, or challenge an idea — keep it specific and respectful.