
Two chokepoints, one exposed island nation
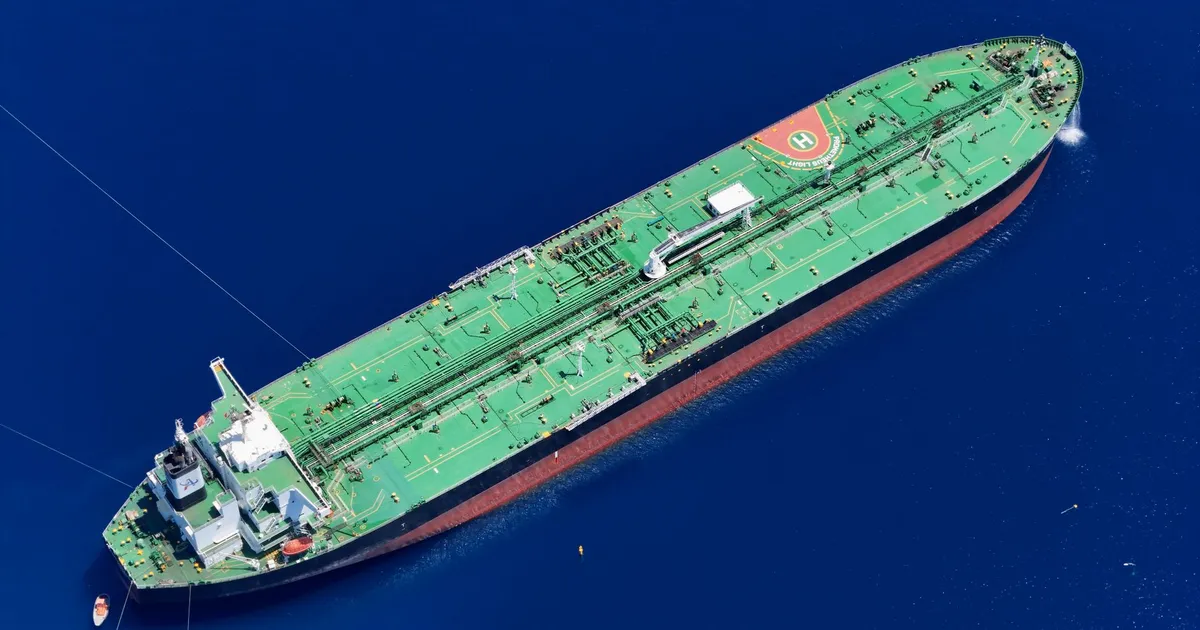
Iran’s Revolutionary Guard struck the Togo-flagged tanker Trend in the Strait of Hormuz on the night of 18 September, citing an “illegal attempt” to transit the strait and warning that vessels passing without authorisation face “destruction”. A second tanker was hit by an “unknown projectile” the day before. This is the most explicit act of chokepoint enforcement since Iran asserted control over much of Hormuz following the conflict that began in late February.
Roughly one-fifth of global oil consumption moves through this corridor. And New Zealand is now exposed at two chokepoints simultaneously: traffic through the Red Sea’s Bab el-Mandeb strait has fallen to 26-35 vessels per day from a prior average of 35-40, with London broker Mohamed Kotb of United Insurance Brokers describing that traffic as “severely impaired and increasingly selective”. This is not distant geopolitics. It is a direct input into what your business pays to move goods.
The number the reassurance hides
The official line is calm. Z Energy chief executive Lindis Jones said on 15 September that “supply remains secure, fuel is still moving, it’s just taking longer and is more expensive to move, so it’s just a story of price not supply security”. He acknowledged safety margins are thinner, inventories are being drawn down and some refineries are deferring maintenance to keep running.
Here is the catch. As of 13 September, New Zealand had roughly 51 days of petrol, 48 days of diesel and 42 days of jet fuel – but that figure counts cargoes still on ships. Fuel on a tanker counts on paper but is not available to consumers if the ship is delayed, diverted or rejected. The in-country picture is much thinner: MBIE data from late July showed just 29.8 days of petrol, 28.1 days of diesel and 30.7 days of jet fuel actually on New Zealand soil. The government’s strategic diesel reserve at Marsden Point is available only until 30 November – ten weeks away.
Prices were already climbing before the strike
Even before this week’s escalation, the pump was biting. Unleaded 91 hit $3.18 a litre on 17 September, its highest since June and up almost 35 cents in 28 days. Westpac senior economist Satish Ranchhod said global fuel markets “have become more volatile in recent weeks”, raising the cost of importing fuel “particularly diesel, alongside higher freight costs and tighter regional supplies”.
Stats NZ figures confirmed the trend: petrol rose 2 percent and diesel nearly 9 percent, the first rise in four months, leaving diesel 46 percent more expensive than a year ago. With fuel making up about 4 percent of the CPI, sustained pressure reads straight through to headline inflation. The Commerce Commission documented the first wave earlier this year, when Brent crude rose from USD $72 to USD $102 a barrel between late February and early May, a 41 percent jump.
The risk most businesses aren’t watching
The transmission mechanism to watch is not a physical blockade. It is insurance. Hamilton Hindin Greene’s analysis earlier in 2026 flagged war-risk insurance as the underappreciated channel: when insurers raise premiums, tighten terms or withdraw cover, shipping becomes uneconomic without a single shot fired. Kotb’s description of Red Sea traffic as “increasingly selective” is that channel already active. A Hormuz strike will trigger immediate reassessment of war-risk premiums for that corridor too.
Dr Dulani Jayasuriya of the University of Auckland Business School put it bluntly in March 2026: “NZ’s just-in-time supply chain works well right up until the moment a Supreme Leader is killed and an insurance underwriter in London stops answering the phone.” She also noted the transmission is fast – when Brent surged 13 percent in early March, it added 3-5 cents a litre at the pump within days.
No refinery, no buffer, no room to relax
New Zealand closed Marsden Point in 2022, converting it to an import terminal that now handles around 40 percent of the country’s fuel supply. Most refined product arrives from Singapore, South Korea and Japan, all of which source crude from the Gulf. That structural choice looks especially exposed now that South Korea is weighing expanded naval operations in the Gulf of Aden to protect its shipping – a supplier whose tanker movements feed directly into New Zealand’s pumps.
Energy expert David Keat, a former Marsden Point manager, warned in July 2026 that global buffer stocks built up before the conflict were largely gone: “it doesn’t take much to tip things over the edge and the price will spike very high”. He likened it to having “no insurance on your house and there’s a storm coming towards you”. That was before the strikes.
The reassurance was credible on 15 September. The strike on the 18th changed the risk calculus. Two chokepoints under pressure, depleted global buffers and an explicit destruction warning is the environment in which boardrooms should be stress-testing fuel, freight and insurance exposure now, not waiting for a formal Phase 2 declaration to make it official.
Sources
- 1News: Iran claims it struck an oil tanker in Strait of Hormuz (2026-09-18)
- Newsroom: Choked Red Sea strait doubles threat to NZ fuel supplies (2026-09-18)
- RNZ: NZ fuel supplies face increased risk, and no price relief (2026-09-15)
- RNZ: Fuel prices see first rise in four months amid renewed US-Iran conflict (2026-09-18)
- NZ Herald: Petrol surges to highest level since June amid ongoing Middle East conflict (2026-09-17)
- RNZ: Oil supplies ‘more precarious’ now than Middle East war outbreak – expert (2026-07-15)
- Commerce Commission: Fuel Price Monitoring 7 May 2026 (2026-05-07)
- Hamilton Hindin Greene: Iran, Oil, and the Chokepoints That Matter (2026-03-27)
- University of Auckland: Global oil chokepoint shows up fragile fuel security (2026-03-07)
Join the discussion
Add useful context, ask a good question, or challenge an idea — keep it specific and respectful.